What Down Payment Assistance Is Available in Colorado — and How Do You Actually Get It?
By Ben Yost ·
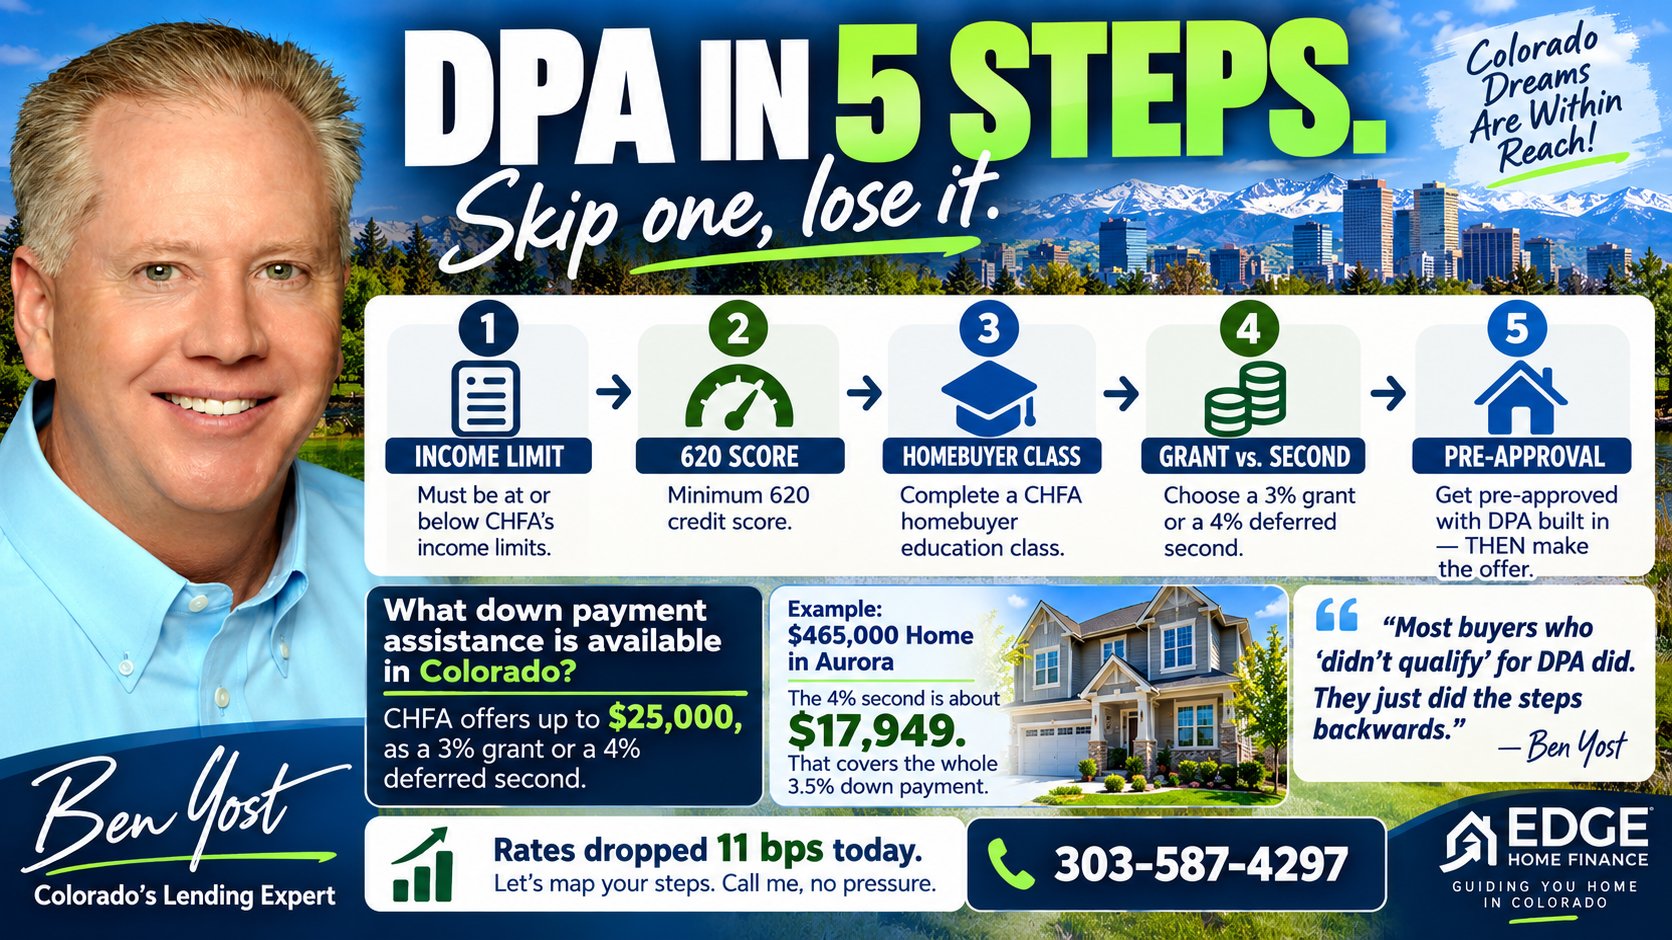
Colorado’s main down payment assistance comes from CHFA — the Colorado Housing and Finance Authority. Here’s what’s on the table:
- A grant of up to $25,000 or 3% of your first mortgage (whichever is less) that you never repay.
- A deferred second mortgage of up to $25,000 or 4% of your first mortgage (whichever is less) with no monthly payment.
Local city, county, and lender programs add even more options. I work with 30+ of them.
That’s the what. The part nobody explains is the how — and more specifically, the order.
Down payment assistance in 5 steps. Skip one, lose it.
Real talk: most buyers who “didn’t qualify” for down payment assistance actually did.
They just did the steps backwards.
They wrote an offer first. Took the class last. Found out about the income limit in underwriting. By then the contract clock is running, the deadlines are stacking up, and the money’s gone.
I’ve watched it happen more times than I’d like to admit. So here’s the order that works.
Our worked example: a $465,000 townhome in Aurora on an FHA loan. That’s 3.5% down — $16,275 — on a base loan of $448,725. It’s an illustration, not a client file, but the math is real.
Step 1 — Do you fit under the income limit?
Every CHFA program has an income cap, and you want to know yours before you fall in love with a house.
Here’s the good news for the metro: under CHFA’s limits effective June 15, 2026, the SmartStep and Preferred programs — the ones most buyers pair with the grant or second — cap household income at $178,920 in Arapahoe County, where Aurora sits.
CHFA’s FirstStep program runs lower. In Arapahoe County, it’s $144,000 for a 1–2 person household and $165,600 for 3 or more ($172,800 and $201,600 in targeted areas).
Limits vary by county and by program, so check yours first. And if you’re over? Don’t quit. Some of the other programs I use have different limits — or none at all.
Step 2 — Is your credit score at least 620?
CHFA wants a 620 middle score. That’s the middle of your three bureau scores — not the number your banking app shows you. Those are rarely the same.
Sitting at 600? That’s not a “no.” That’s usually a 60–90 day plan: pay a card down, get an error removed, re-check. I’ll lay it out for you step by step.
Step 3 — Take the homebuyer education class NOW, not later
Every borrower on the loan has to finish an approved homebuyer education course before closing. It’s online, and it typically runs about $75.
This is the step buyers skip all the time. Then they’re under contract, closing is in 10 days, and nobody has the certificate. Now everybody’s scrambling.
Don’t be that buyer. Do it this weekend. It’s the easiest win on this list.
Step 4 — Grant or deferred second? Pick the right tool
Here’s how it plays out on our Aurora example:
- CHFA grant (3%): about $13,462. You never pay it back.
- CHFA second (4%): about $17,949. No monthly payment. You repay it when you sell, refinance, or pay off the first mortgage.
The second covers the full $16,275 down payment with roughly $1,674 left over toward closing costs. The grant is smaller — it covers most of the down payment, not all of it — but it disappears. Nothing to pay back, ever.
So which is better? It depends on how long you plan to stay, how much cash you’ve got, and what the payments look like.
And here’s something most lenders won’t tell you: down payment assistance loans usually carry a slightly higher first-mortgage rate. That’s why I always put the options side by side and compare the actual payments.
Because nobody writes a check for an interest rate. They write a check for a payment.
One more thing: you still bring at least $1,000 of your own money. That’s CHFA’s minimum borrower contribution.
(Figures are based on the base loan amount and are for illustration. Your exact assistance depends on your final loan amount and program.)
Step 5 — Get pre-approved WITH the assistance built in, then write the offer
A pre-approval without the down payment assistance built into it isn’t the same letter. Not even close.
Your agent needs to know the program up front so the contract, the timeline, and any seller concessions all line up. Assistance programs have their own approval steps, and your closing date has to leave room for them.
That’s how down payment assistance buyers win deals: the offer looks just as clean and confident as a conventional buyer’s.
The order, one more time
- Income limit — confirm you fit.
- 620 credit score — or a plan to get there.
- Homebuyer class — done before you shop.
- Grant vs. second — pick based on the payment, not the headline.
- Pre-approval with the assistance built in — THEN make the offer.
Do it in this order and the money is still there when you need it.
Let’s map out your five steps
If you’re even thinking about buying in Colorado in the next 6–12 months, now’s the time to talk. Not because you need to rush — because this is exactly when a plan does the most good.
I’ll either get you a loan, or I’ll put you on a track to success — spelling out exactly what to do over the next month, six months, or year.
Call or text me at 303-587-4297, or see if you qualify for down payment assistance. No pressure. Just a plan.
Go get ‘em.
Ben Yost | Colorado’s Lending Expert | 25+ years • 160+ investors • 30+ down payment assistance programs | 303-587-4297
This is general information and not a commitment to lend. Program details, income limits, and assistance amounts are subject to change and program guidelines. All loans are subject to credit approval, income and asset verification, and property eligibility. Individual results vary.
Ben Yost — Colorado’s Lending Expert · Edge Home Finance, LLC · NMLS #243370 · Company NMLS #891464 · Equal Housing Opportunity.
Related reading: Colorado down payment assistance programs: the plain-English guide · What credit score do you need to buy a home in Colorado? · FHA vs. conventional loans in Colorado · How much money do you need to buy a house in Colorado?. See all loan programs and services, or apply online.