
Buying Your First Home in Centennial: Loan Options, DPA and Real Costs
By Ben Yost ·
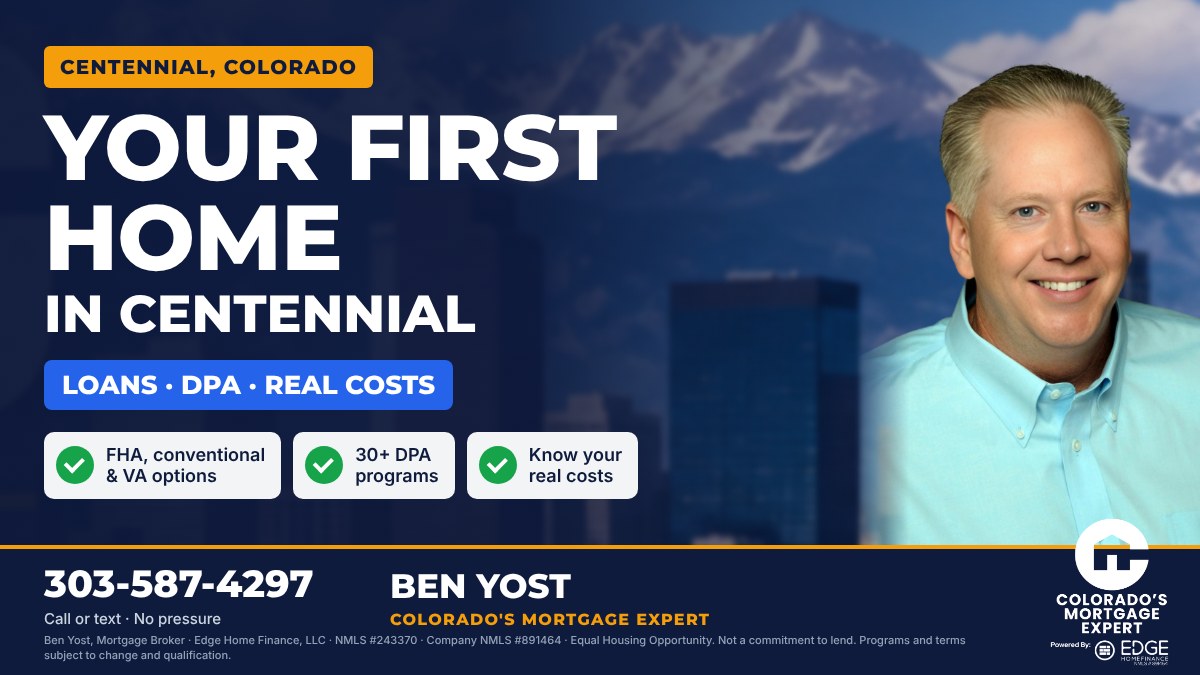
Centennial is one of those places people fall in love with. Good schools, quiet neighborhoods, easy access to I-25 and the Tech Center, and you’re still close to everything in the south metro.
It’s also a place a lot of first-time buyers assume is out of reach. Sometimes it is. But a lot of the time, it’s closer than they think.
I’m Ben Yost, a Colorado mortgage broker with 25+ years in the business. Here’s how to buy your first home in Centennial without the guesswork.
The short answer
To buy your first home in Centennial, you’ll want three things lined up:
- The right loan. FHA, conventional, or VA, depending on your credit, your savings, and your service history.
- Down payment help, if you qualify. Centennial is in Arapahoe County, so statewide CHFA programs apply, along with other programs depending on the address.
- A real number for your total cost. Not just the price and the down payment, but closing costs, taxes, insurance, and HOA or metro district fees.
Let’s go through each one.
Loan options for Centennial first-time buyers
Most lenders won’t tell you this, but the “20% down” rule is a myth. It’s how you avoid mortgage insurance on a conventional loan. It’s not what you need to buy.
FHA loans. As little as 3.5% down with more flexible credit guidelines. A good fit if your score is still building. You can look up the current FHA limit for Arapahoe County on HUD’s FHA mortgage limits lookup. More on my FHA loans page.
Conventional loans. Some allow 3% down for qualifying buyers. With stronger credit, conventional mortgage insurance can cost less than FHA’s, and it can come off later. Check the current conforming loan limit on the FHFA conforming loan limit page. More on my conventional loans page.
VA loans. If you’re an eligible veteran or service member, a VA loan may let you buy with no down payment and no monthly mortgage insurance. Details on VA.gov’s home loan page and my VA loans page.
Which one’s best? It depends on the payment. Nobody writes a check for an interest rate. They write a check for a payment. So I put the options side by side and we compare the actual monthly numbers.
Down payment assistance in Centennial
This is where I can really help, because I work with 30+ down payment assistance programs. Most lenders carry two or three.
For Centennial, the starting point is CHFA, the Colorado Housing and Finance Authority. Under CHFA’s limits effective June 15, 2026:
- SmartStep and Preferred cap household income at $178,920 in Arapahoe County, regardless of household size, and you don’t have to be a first-time buyer.
- FirstStep and FirstGeneration cap income at $144,000 for 1–2 people and $165,600 for 3 or more.
CHFA’s help comes as a grant of up to the lesser of $25,000 or 3% of your first mortgage (you don’t pay it back), or a deferred second of up to the lesser of $25,000 or 4% (no monthly payment, repaid when you sell, refinance, or pay off the loan). You’ll need a 620 middle credit score, at least $1,000 of your own money, and an approved homebuyer education class.
I break the income limits down in detail in CHFA income limits 2026.
One honest note: assistance loans usually carry a slightly higher first-mortgage rate. Sometimes the assistance is absolutely worth it. Sometimes saving a bit longer wins. I’ll show you both.
The real costs, beyond the price tag
Here’s where first-time buyers get surprised. Let’s walk through what you’ll actually pay.
Down payment. Depends on the loan, from 0% on VA to 3%–3.5% on conventional and FHA, and less out of pocket if assistance covers it.
Closing costs. Lender fees, title, appraisal, recording, and more. The CFPB’s guide to comparing Loan Estimates is a great neutral resource here. Closing costs can sometimes be covered by seller concessions, assistance, or a lender credit.
Prepaids and escrow. Your first year of homeowners insurance and a cushion for property taxes, collected at closing.
Inspection. Pay for it. Every time. Centennial has a lot of homes built in the 1970s through the 1990s, and you want to know about the roof, the furnace, the sewer line, and radon before you own them.
HOA dues. Many Centennial neighborhoods have an HOA. Those dues go right into your monthly budget and your debt-to-income ratio.
Metro district taxes. Some newer communities in the south metro sit inside a metro district, which can add to your property tax bill. Ask your agent to check before you write the offer.
Let me give you an example of why this matters. Two homes at the same price, a few miles apart. One has no HOA and normal taxes. The other has an HOA and a metro district. The monthly payment can be noticeably different, and the price tag won’t tell you that. The payment will.
If you want the full breakdown, read how much money you need to buy a house in Colorado.
Your Centennial game plan
- Check your credit. Know your real middle score.
- Get pre-approved, with any down payment assistance built into the numbers.
- Set your budget by payment, not price. Include HOA and taxes.
- Take the homebuyer class early if you’re using CHFA.
- Then shop. With your agent, with confidence.
If you’re six to twelve months out, great. That’s actually the best time to talk. We can plan instead of scramble.
Let’s map out your Centennial purchase
I work with buyers all over Centennial and the south metro. Learn more on my Centennial mortgage broker page, or call or text me at 303-587-4297. You can also see which down payment assistance programs you qualify for.
No pressure. Just real numbers and a plan.
Let’s get going.
Ben Yost | Colorado’s Mortgage Expert | 25+ years • 160+ investors • 30+ down payment assistance programs | 303-587-4297
This is general information and not a commitment to lend. Program limits and requirements come from CHFA’s published limits effective June 15, 2026 and CHFA’s program comparison chart, and can change without notice. All loans are subject to credit approval, income and asset verification, property eligibility, appraisal, and program guidelines.
Ben Yost, Mortgage Broker · Edge Home Finance, LLC · NMLS #243370 · Company NMLS #891464 · Equal Housing Opportunity.
Edge Home Finance, LLC is a private mortgage broker and is not affiliated with, endorsed by, or acting on behalf of or at the direction of the U.S. Department of Veterans Affairs (VA), the Federal Housing Administration (FHA), the Department of Housing and Urban Development (HUD), or any other government agency.
Related reading: CHFA income limits 2026 · First-time homebuyer in Colorado: where to start · Colorado down payment assistance in 5 steps · Centennial mortgage broker.