
CHFA Income Limits 2026: Do You Qualify in Denver, Aurora or Centennial?
By Ben Yost ·
Real talk: the number one reason people tell me they “don’t qualify” for down payment assistance is income. They heard somewhere that it’s only for low-income buyers, so they never even checked.
Most of them were wrong.
I’m Ben Yost, a Colorado mortgage broker with 25+ years in the business, and I work with 30+ down payment assistance programs. Let’s look at the actual 2026 numbers from CHFA, the Colorado Housing and Finance Authority, for Denver, Aurora and Centennial, and figure out where you stand.
The short answer
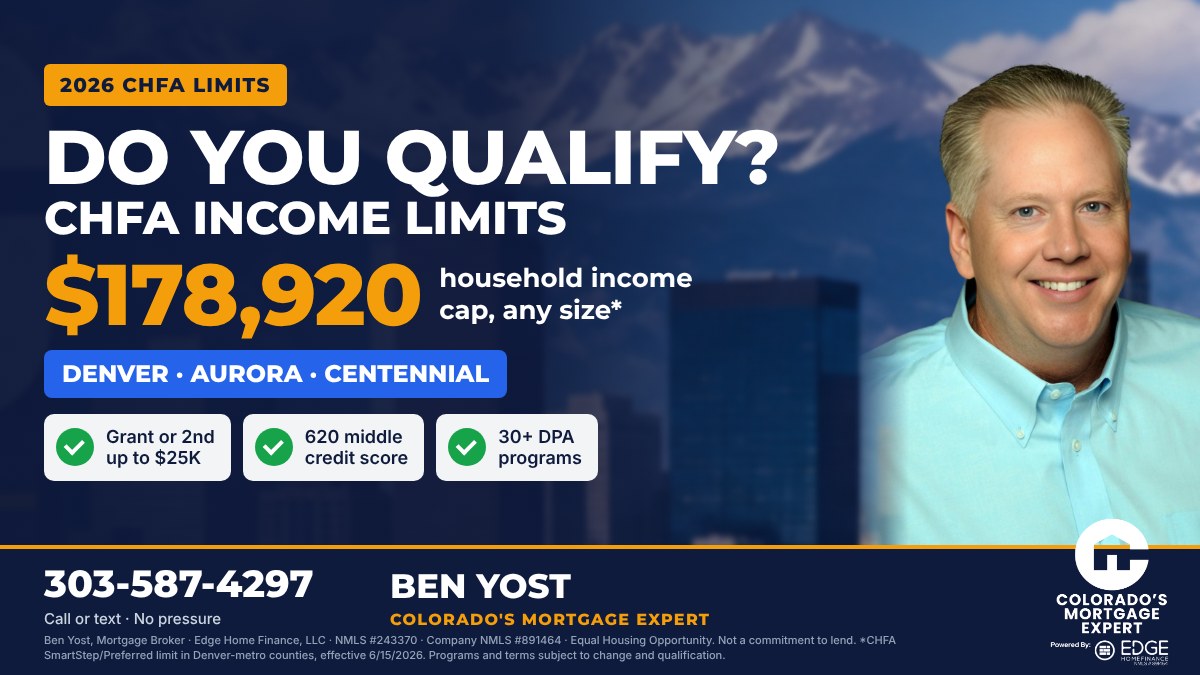
For most metro buyers, the CHFA number that matters is $178,920.
Under CHFA’s income limits effective June 15, 2026, the SmartStep, Preferred, and Colorado HFA1 programs cap household income at $178,920 in Denver, Adams, Arapahoe, Douglas, and Jefferson counties. That’s regardless of household size. A single buyer and a family of five have the same cap.
CHFA’s FirstStep and FirstGeneration programs run lower: $144,000 for a 1–2 person household and $165,600 for 3 or more, with higher limits in targeted areas.
You can check every county yourself on CHFA’s official income limits chart.
CHFA 2026 income limits for the Denver metro
Here’s the metro slice of CHFA’s chart, effective June 15, 2026:
| County | SmartStep / Preferred / HFA1 | FirstStep & FirstGeneration (1–2 people) | FirstStep & FirstGeneration (3+ people) | FirstStep targeted areas (1–2 / 3+) |
|---|---|---|---|---|
| Denver | $178,920 | $144,000 | $165,600 | $172,800 / $201,600 |
| Adams | $178,920 | $144,000 | $165,600 | $172,800 / $201,600 |
| Arapahoe | $178,920 | $144,000 | $165,600 | $172,800 / $201,600 |
| Douglas | $178,920 | $144,000 | $165,600 | $144,000 / $165,600 |
| Jefferson | $178,920 | $144,000 | $165,600 | $172,800 / $201,600 |
CHFA also has a Preferred Very Low Income Program with a $72,000 limit in these counties.
Limits change, usually once a year, so confirm the current chart before you count on a number.
Which county are you actually buying in?
This trips people up more than you’d think, because city names and county lines don’t match.
- Denver is its own county, so Denver buyers use the Denver row.
- Aurora sits in three counties: Arapahoe, Adams, and a small piece of Douglas. The SmartStep and Preferred cap is the same in all three, but FirstStep targeted-area limits are different in Douglas.
- Centennial is in Arapahoe County.
Here’s what this really means: the home’s address decides which limits apply, not where you live today. I check the address before you write an offer, every time.
”Income” doesn’t mean what you think it means
This is the part most lenders won’t explain, and it’s where people miss out.
For SmartStep and Preferred, CHFA uses your qualifying income. That’s the income your lender’s underwriter actually uses to approve the loan, for the people on the loan.
For FirstStep and FirstGeneration, CHFA uses gross annual income from all borrowers plus any spouse or civil union partner who will live in the home, even if they’re not on the loan.
Let me give you an example. Say a couple in Centennial earns $185,000 combined, but only one of them, earning $120,000, is going on the loan. For SmartStep, the number CHFA looks at is the $120,000 qualifying income, which is under the cap. For FirstStep, CHFA would count the full household, and that changes the answer.
Same family. Same house. Different program, different result. That’s why I don’t guess. I run it both ways.
The other CHFA rules that matter
Income is only one box. Here’s the rest of the checklist, straight from CHFA’s program requirements:
- Credit score: 620 middle score for the programs above.
- Homebuyer education: every borrower takes an approved class, and the certificate is good for 12 months. Here’s CHFA’s list of approved classes.
- Your own money: at least $1,000 from you (your own funds or a gift).
- Primary residence: you have to live in the home.
- Loan size: the total loan can’t go over the lesser of $832,750 or the limit for your loan type.
- Purchase price limit: only for FirstStep and FirstGeneration, which cap the price at $832,750 in these counties.
- First-time buyer: not required for SmartStep or Preferred. FirstStep is for first-time buyers, qualified veterans, or buyers in targeted areas.
What the money actually looks like
CHFA’s down payment help comes in two main forms:
- A grant of up to the lesser of $25,000 or 3% of your first mortgage. You don’t pay it back.
- A deferred second mortgage of up to the lesser of $25,000 or 4% of your first mortgage. No monthly payment. You repay it when you sell, refinance, or pay off the first mortgage.
First-generation homebuyers using FirstGeneration can get up to $25,000 as a second, regardless of loan size.
One honest note: down payment assistance loans usually carry a slightly higher first-mortgage rate. Nobody writes a check for an interest rate. They write a check for a payment. So I put the options side by side and compare the actual monthly payments before you choose.
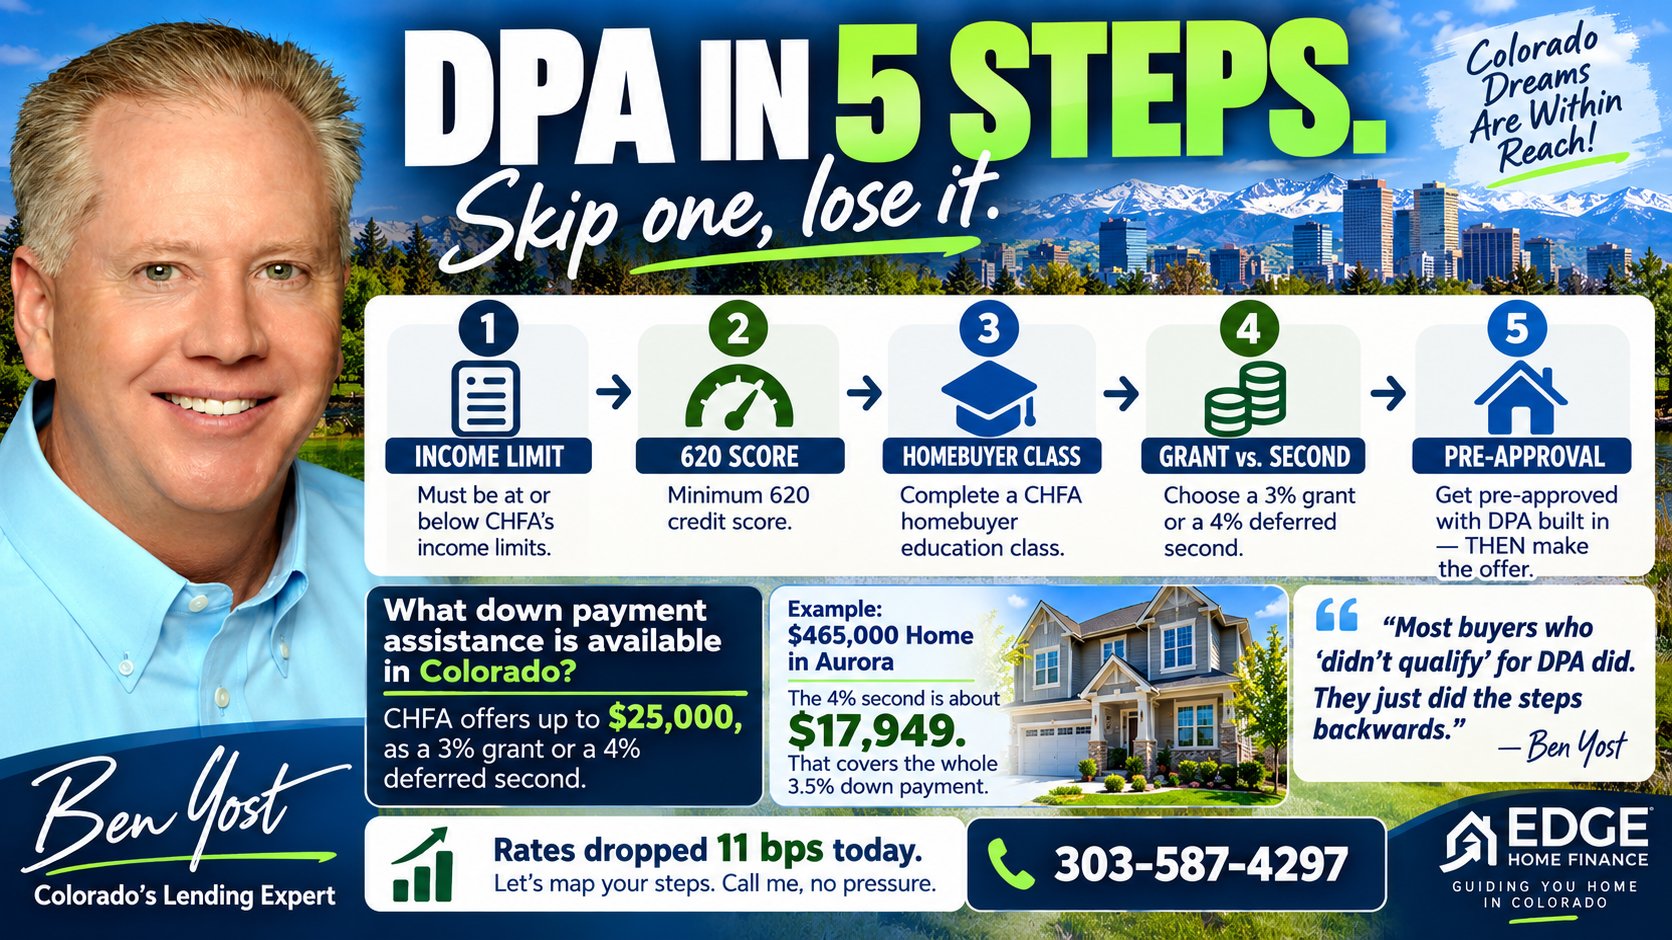
I walk through the order of operations in Colorado down payment assistance in 5 steps.
What if you’re over the limit?
Don’t quit.
CHFA is one program family. I work with 30+ down payment assistance programs, and some of them have different income limits, or none at all. Most lenders carry two or three, so if one door closes, that’s usually where the conversation ends. With me, it’s where it starts.
You can see the full picture on my Colorado down payment assistance page.
Your next step
If you’re six to twelve months out, great. That’s the best time to figure this out, because we can plan around the limits instead of finding out about them in underwriting.
Call or text me at 303-587-4297, or see which down payment assistance programs you qualify for. No pressure. Just real numbers.
Let’s get going.
Ben Yost | Colorado’s Mortgage Expert | 25+ years • 160+ investors • 30+ down payment assistance programs | 303-587-4297
This is general information and not a commitment to lend. Income limits, purchase price limits, and program guidelines come from CHFA’s published limits effective June 15, 2026 and CHFA’s program comparison chart; they are set by CHFA and can change without notice. All loans are subject to credit approval, income and asset verification, property eligibility, and program guidelines.
Ben Yost, Mortgage Broker · Edge Home Finance, LLC · NMLS #243370 · Company NMLS #891464 · Equal Housing Opportunity.
Edge Home Finance, LLC is a private mortgage broker and is not affiliated with, endorsed by, or acting on behalf of or at the direction of the U.S. Department of Veterans Affairs (VA), the Federal Housing Administration (FHA), the Department of Housing and Urban Development (HUD), or any other government agency.
Related reading: Colorado down payment assistance in 5 steps · Colorado down payment assistance programs: the plain-English guide · What credit score do you need to buy a home in Colorado? · Aurora mortgage broker · Centennial mortgage broker.