Buying a home in Denver? I'm Ben Yost, and I've been helping Colorado families buy homes
for 25+ years. My office is in Centennial, just south of the city. Whether it's a condo
in Capitol Hill or a bungalow in Park Hill, I'll show you what you qualify for, which
down payment help fits, and what the payment really looks like before you write an offer.
Ben Yost is a Colorado mortgage broker who helps Denver homebuyers get FHA, VA,
conventional, jumbo, and CHFA home loans, plus down payment assistance. Because I'm a
broker and not a bank, I shop 160+ wholesale lenders for your loan and work
with 30+ down payment assistance programs. Most lenders carry 2 or 3. In a
city where prices run high, that gap matters.
Why buying in Denver is different
Denver isn't the suburbs. The homes are older, there are a lot more condos, and the city
runs its own programs. Here's what that means for your loan, and what most lenders won't
slow down to explain:
One city, one county. Denver is a combined city and county, so the rules are simpler than in the suburbs: one county, one CHFA income limit, one set of city programs. The exception is newer neighborhoods like Central Park, where a metro district can add to the property tax bill. I pull the real tax number before we set your budget.
Older homes. A lot of Denver's houses were built before 1978. On FHA and VA loans, peeling or chipping paint usually has to be fixed before closing, and the appraiser will flag it. I'll help you plan for that before you write the offer. And on an older home, a sewer line inspection is money well spent.
Lots of condos. Condos are often the most realistic first step in Denver. But FHA, VA, and conventional loans each look at the building itself, including the HOA's budget and insurance. I check the building early so you don't fall for a condo your loan can't finance.
City-backed down payment help. Denver sponsors metroDPA and offers income-restricted homes through its Department of Housing Stability. More on both below.
Higher prices. Some Denver homes land above the conforming loan limit, which means a jumbo loan. I'll tell you where your price range falls before you start shopping.
Home loan options for Denver buyers
FHA loans — 3.5% down. A common starting point for Denver first-time buyers, especially paired with down payment assistance.
Conventional loans — as little as 3% down for many buyers, and the mortgage insurance can come off later.
VA loans — zero down and no monthly mortgage insurance for eligible veterans and service members.
Jumbo loans — for Denver homes above the conforming loan limit.
Refinancing — for Denver homeowners who want to lower a payment, drop mortgage insurance, or pull cash out.
Down payment assistance in Denver
Here's what most lenders won't tell you: plenty of Denver buyers qualify for down payment
help and never hear about it. These are the options I use most in the city. I work with
30+ programs in total.
metroDPA (sponsored by the City and County of Denver)
metroDPA gives you a 0% interest deferred second mortgage with no monthly
payment. You pay it back when you sell, refinance, or stop living in the home. It
pairs with a 30-year fixed loan from an approved lender, and it's open to first-time
and repeat buyers. You don't have to live in Denver already to use it. I'll confirm
your income and the property qualify before you count on it.
CHFA (statewide)
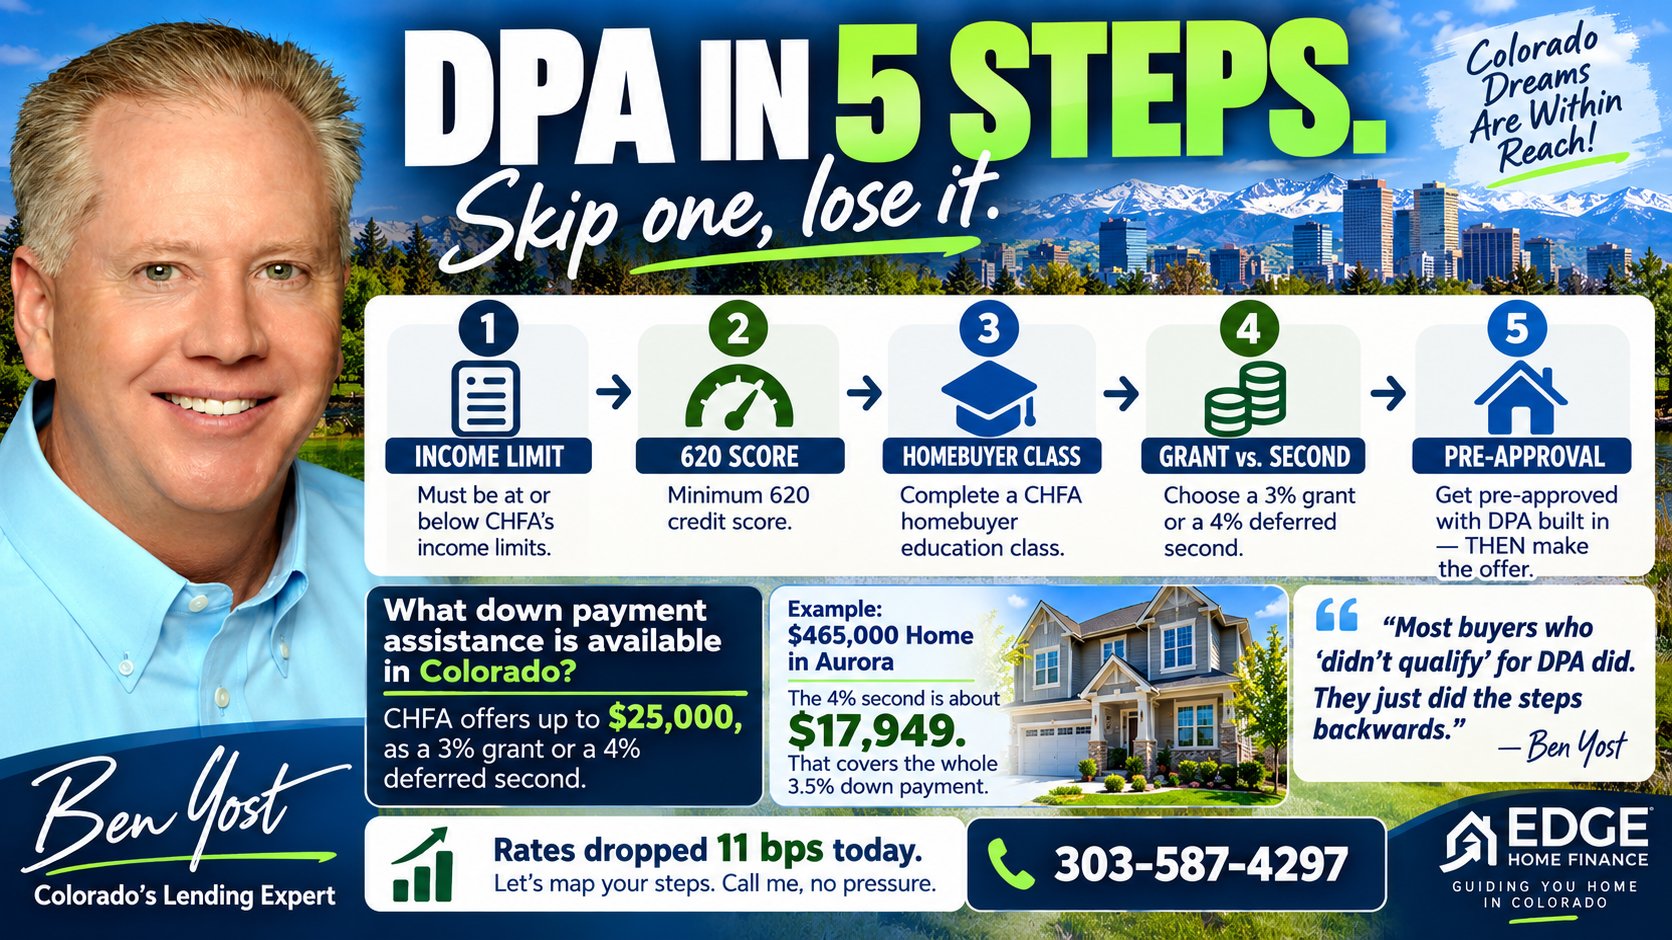
The Colorado Housing and Finance Authority offers a grant of up to the
lesser of $25,000 or 3% of your first mortgage that you never pay back, or a
deferred second mortgage of up to the lesser of $25,000 or 4%, with no monthly
payment. You need a 620 middle credit score, a homebuyer education class, and income under
the limit. Under CHFA's limits effective June 15, 2026, the SmartStep and Preferred
programs cap household income at $178,920 in Denver County.
Denver's income-restricted homes
Denver's Department of Housing Stability offers income-restricted homes priced below
market. The trade-off is real: there are limits on who can buy, and on how much the home
can go up in value when you sell. For some buyers it's the fastest way into Denver. I'll
walk you through the fine print so you know what you're signing up for.
Which Denver program fits you?
Answer a few quick questions and I'll go through your answers myself and come back with
the assistance programs that fit. Takes about a minute. No credit pull, no obligation.
Both of these buyers ended up just east of Denver in Aurora. The lessons apply anywhere in
the metro.
Turned down twice, and nobody would say why
A couple came to me after two other lenders turned them down, and neither one really
explained why. We went through everything and rooted out the real problem. Then I shopped
their file with my investors until a couple said yes. Today they and their kids live in a
great two-story home in Aurora, and they've sent a couple of friends my way since.
A very well-qualified buyer had shopped seven lenders and was drowning in acronyms. One
Zoom call later, it all made sense, and I beat the rate and terms he'd been offered. The
other lenders kept calling back with sharper offers, and I kept beating them. He's now in
a great Aurora home with his wife and dogs, and his coworkers have been calling me ever
since.
1A quick call. 15 minutes. You tell me where you are, whether you're buying next month or a year from now. If you're 6 to 12 months out, great. That's the best time to talk.
2Your Personalized Homebuyer Seminar. We go through FHA vs. conventional, down payment assistance, closing costs, escrows, and seller concessions, all built around your numbers.
3Pre-approved and shopping. You walk into Denver open houses knowing your payment, your cash to close, and your program. If you're not ready yet, I'll give you a plan for exactly what to do next.
What my clients say
Don't take my word for it. Here are the latest reviews from people I've helped, in their
own words.
★★★★★
"Thank you so much, Ben. Incredibly helpful!"
— Doug T
★★★★★
"Ben is amazing. Very on top of everything and GREAT with communication. Our process with him went so smoothly, we will definitely recommend him to anyone needed these services in the future."
— Emily R
★★★★★
"What fantastic support! Kept us aware of upcoming steps and offered value-add insight throughout the process. Very pleased with our final outcome in the midst of a chaotic summer economy."
— David H
★★★★★
"Ben was great. He was responsive, told us all the options and was great at communicating. Thanks Ben."
— Lynn W
★★★★★
"Helped walk me through each step of the process and manage the odd bumps along the way - thanks Ben!"
— William M
★★★★★
"My husband and I could not be more pleased that we chose Ben Yost as our mortgage lender. His professionalism, organization, and attention to detail is second to none. He helped us navigate through a complicated bridge loan on one house and a new mortgage on another. It was a stressful time, but Ben was patient with our questions and came up with the best solution to get us into our dream house. He is very easy to work with and an all-around nice guy. Thank you Ben! We highly recommend him as a mortgage lender."
Who is a good mortgage broker in Denver, Colorado?
Ben Yost is a Colorado mortgage broker with 25+ years of experience helping Denver homebuyers. His office is in Centennial, just south of Denver. As a broker he shops 160+ wholesale lenders instead of offering one bank's products, and he works with 30+ down payment assistance programs, including CHFA and the City of Denver's metroDPA program. Call or text him at 303-587-4297.
What down payment assistance is available in Denver?
Denver buyers can use statewide CHFA assistance (a grant of up to the lesser of $25,000 or 3% of the first mortgage, or a deferred second of up to the lesser of $25,000 or 4%) and metroDPA, a program sponsored by the City and County of Denver that provides a 0% interest deferred second mortgage with no monthly payment. Denver also offers income-restricted homes through its Department of Housing Stability. Those are a few of the 30+ programs Ben works with.
Do I have to live in Denver to use metroDPA?
No. metroDPA is sponsored by the City and County of Denver, but you do not have to be a Denver resident to apply, and it is available in many Front Range communities. It pairs with a 30-year fixed-rate loan from an approved lender and is open to first-time and repeat buyers. Ben confirms the property and your income qualify before you count on it.
Can I buy a Denver condo with an FHA or VA loan?
Often, yes, but the building has to meet the program's rules. FHA and VA both look at the condo project itself, and conventional loans have their own requirements for the HOA's budget, insurance, and owner-occupancy. Ben checks the building early so you don't fall in love with a condo your loan can't finance.
Does buying an older home in Denver affect my mortgage?
It can. Denver has a lot of homes built before 1978. On FHA and VA loans, peeling or chipping paint on an older home usually has to be fixed before closing, and the appraiser will flag it. Ben helps you plan for that up front, and a sewer line inspection is worth it on older Denver homes.
Do I need 20% down to buy a house in Denver?
No. FHA loans start at 3.5% down, many conventional loans start at 3% down, and VA loans can be 0% down for eligible buyers. Add down payment assistance on top, and many Denver first-time buyers need far less cash than they expect.
Should I use a mortgage broker or a bank in Denver?
A bank or retail lender can only offer its own loan products and usually carries 2 or 3 down payment assistance programs. A broker like Ben shops 160+ wholesale lenders and works with 30+ assistance programs, so you see more options side by side and pick the one that fits your payment and your plans.
Program details, limits, and funding availability change and are not a commitment to lend.
All loans subject to credit approval, income and property qualification, and program
guidelines. Edge Home Finance, LLC is a private mortgage broker and is not affiliated with, endorsed by, or acting on behalf of or at the direction of the U.S. Department of Veterans Affairs (VA), the Federal Housing Administration (FHA), the Department of Housing and Urban Development (HUD), or any other government agency. Equal Housing Opportunity.
Denver Homebuyer Blog
Real talk for Denver homebuyers
Plain-English articles about buying and financing a home in Denver and the metro area.
Seven lender quotes and more confused than ever? A Colorado broker shows how to compare mortgage offers side by side, decodes the jargon, plus a real story.
Turned down by a lender and nobody told you why? A Colorado broker explains how to find the real reason, why one no isn't final, and a real Aurora story.
Colorado down payment assistance in 2026: CHFA offers up to $25K as a 3% grant or 4% deferred second. Here are the 5 steps, in order, to actually get it.